Fire & Smoke Damage in Laredo, TX
A fire claim is rarely settled on what you can see, because smoke and soot travel well past the burned room. We inspect the loss ourselves and document every affected room, so the carrier answers an independent estimate instead of working from its own alone.
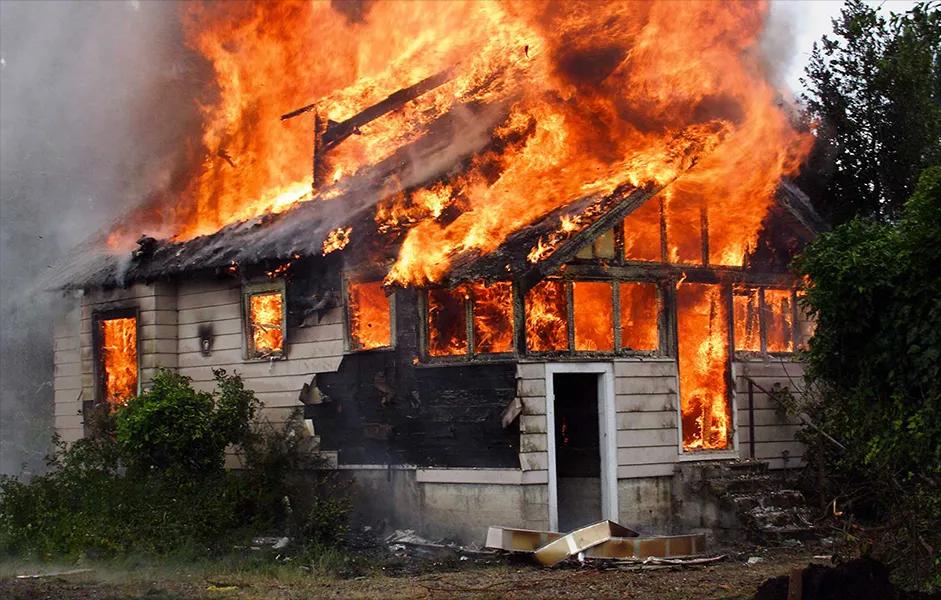
Fire in a Laredo, Texas masonry building is deceptive. Block and stone may stand while heat weakens framing above the ceiling, and soot moves through ducts and cavities into rooms that look clean. We document the damage from outside in, with wipe tests and room by room smoke mapping, plus air handler and attic conditions. On a business property we also gather the records behind lost income and the cost of working elsewhere. For a house we track temporary housing, storage and meals. Webb County property owners who want an independent fire estimate can call us or send the free claim review form from anywhere near the Rio Grande.
What a carrier's inspection tends to miss on fire & smoke damage claims in Laredo
- 01
Smoke through wall cavities
Soot can move through framing and ductwork into rooms the fire never reached, and an estimate written for the burned room can leave those rooms out.
- 02
Soot bonded to the HVAC system
Ducts and air handlers may need testing, cleaning or replacement, and they are easy to leave off a room-by-room estimate.
- 03
Heat damage above the ceiling
Wiring, framing and insulation can be compromised where nothing looks burned from below.
- 04
Code upgrades on the rebuild
A house is rebuilt to current code, and ordinance and law coverage, where a policy has it, often has to be requested in writing.
- 05
Additional living expense
Hotel, rental, storage and the higher cost of meals while the kitchen is unusable are costs many people never think to claim.
- 06
Contents priced as depreciated cash
A contents list without age, condition and replacement pricing can leave a figure that does not replace what was lost.
What gets documented on fire & smoke damage claims in Laredo
- Charring depth and heat-affected framing
- Room-by-room smoke and soot mapping, with wipe testing
- HVAC, ductwork and attic condition
- Odor in porous materials and insulation
- Contents inventory with age, condition and replacement price
- Additional living expense receipts and dates
- Code upgrade items on the rebuild
- Recoverable depreciation holdback and its paperwork
- Business interruption records on commercial losses
Which policy pays for fire damage
Questions about fire & smoke damage claims in Laredo
Answer 01
Under many Texas homeowners policies, smoke and soot from a covered fire are part of the fire loss. The common problem is scope. Smoke travels well beyond the burn area, so it has to be tested and documented room by room before it appears on an estimate. Your own policy language controls, and we read it in the free review.
Under many Texas homeowners policies, smoke and soot from a covered fire are part of the fire loss. The common problem is scope. Smoke travels well beyond the burn area, so it has to be tested and documented room by room before it appears on an estimate. Your own policy language controls, and we read it in the free review.
Stay out of the structure until the fire department releases it. After that, photograph and video every room from several angles, including rooms that look untouched. Report the loss to your carrier and write down the claim number, the adjuster's name and the date. Keep every receipt from the day of the fire.
It is a coverage found in many homeowners policies that can reimburse costs of living elsewhere while a home is unlivable, such as lodging, storage, pet boarding and extra meal costs. Limits and conditions vary by policy, and receipts make it far easier to document than memory does.
Yes. Masonry walls can look intact while heat has affected framing, wiring or insulation above the ceiling, and smoke can settle in ducts and wall cavities. Thorough inspection looks at these hidden parts before a scope of repair is accepted.
Some commercial property policies include business income and extra expense coverage while the premises are unusable. Terms and limits vary a great deal. Keep financial records, and ask us to check whether your policy includes this coverage.