Water Damage in Santa Fe, TX
Water claims often turn on one question: was the loss sudden and accidental, or gradual? We record moisture readings, the failed component and the affected materials early, because mitigation removes that evidence within days.
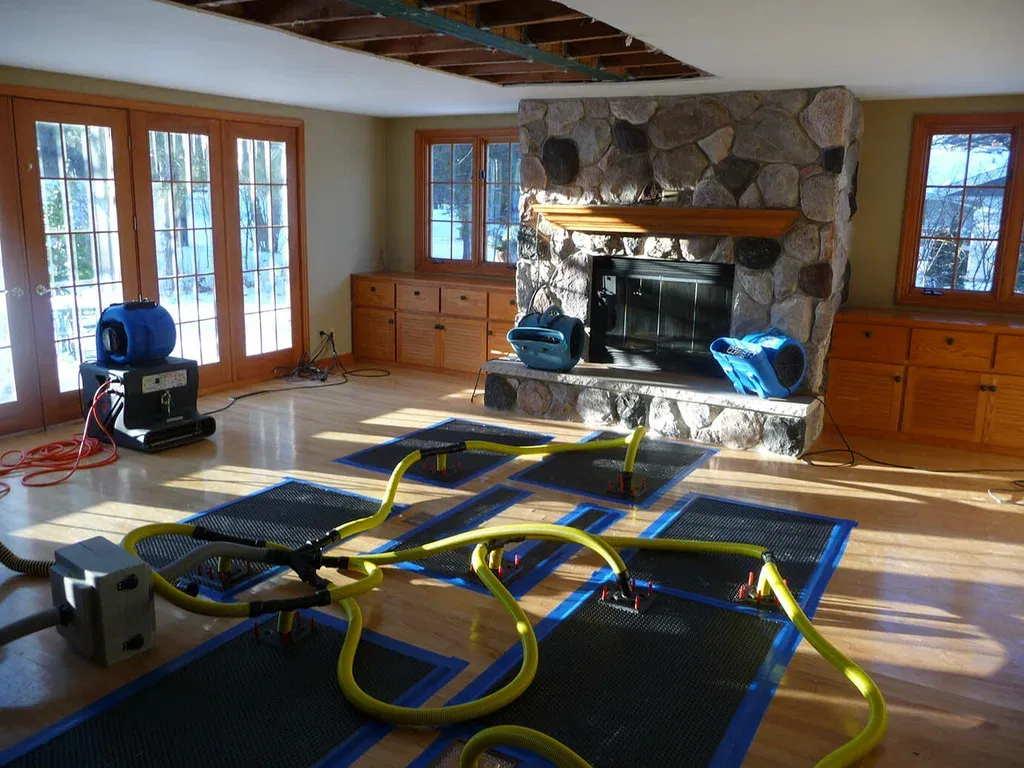
Water damage in a Santa Fe, Texas home can start from a burst pipe, a failed appliance line or a storm-damaged roof, and slow Gulf Coast drainage outside does not make the inside any easier to dry. In a single-story home along State Highway 6, one leak can run under flooring and into several rooms. We take moisture meter and thermal readings, keep the failed part when we can, and record how the materials look, since insurers often argue a leak was gradual instead of sudden. Water rising from outside is flood, a different policy. If you found water inside, call us or send the claim review form before repairs start.
What a carrier's inspection tends to miss on water damage claims in Santa Fe
- 01
Wet material behind the surface
Wall cavities, subfloor and cabinet bases can hold water long before any stain shows.
- 02
The failed part was thrown away
The fitting or pipe shows how the loss happened, and it is hard to rebuild that story once it is gone.
- 03
A gradual leak finding made on day sixty
Corrosion, moisture gradients and the state of the materials speak to duration, and they are easiest to capture early.
- 04
Mitigation invoices cut as excessive
Drying charges can be checked against industry drying standards before they are reduced.
- 05
Slab leak access costs
Some policies pay for tearing out and restoring the slab and flooring to reach a leak, even where the pipe itself is excluded.
- 06
Flooring that cannot be matched
Where a run of flooring cannot be repaired invisibly, the scope question is the continuous area.
What gets documented on water damage claims in Santa Fe
- Moisture meter readings across affected assemblies
- Thermal imaging of walls, ceilings and floors
- The failed pipe, fitting or appliance, photographed and kept where possible
- Corrosion and duration indicators
- Wall cavity, subfloor and cabinet substrate condition
- Drying equipment logs and mitigation invoices
- Flooring layout and continuity
- Mold limits and secondary growth from the covered event
Local exposure in Santa Fe
Flooding from heavy rain
Flat Gulf Coast terrain in Galveston County means heavy rain drains slowly, which puts flood and water claims on the table after major storms.
Which policy pays for water damage
Questions about water damage claims in Santa Fe
Answer 01
Many Texas homeowners policies cover water that escapes suddenly and accidentally from plumbing or appliances, including resulting damage. The cost to repair the failed pipe itself is often excluded, as is damage from long-term seepage. Your policy wording controls.
Many Texas homeowners policies cover water that escapes suddenly and accidentally from plumbing or appliances, including resulting damage. The cost to repair the failed pipe itself is often excluded, as is damage from long-term seepage. Your policy wording controls.
Water damage starts inside the property, such as a burst supply line, an overflowing appliance or a roof leak during a storm. Flood is rising surface water from outside, including storm surge and bayou overflow, and it generally requires a separate NFIP or private flood policy.
It can be where the physical evidence points to a sudden failure. Moisture gradients, the condition of the failed part, corrosion and the extent of any growth all say something about duration. The sooner that evidence is captured, the better it holds up.
Yes, if you safely can. The failed pipe, fitting or appliance part shows how the water escaped and helps answer a claim that the leak was gradual. Photograph it where it failed, bag it, and tell your plumber you want it saved.
Probably not. Rain water rising from the ground outside is generally flood, which standard homeowners policies commonly exclude and a separate flood policy may cover. Water that falls through a roof opening or leaks from plumbing inside is treated differently. We read the policy to sort out which applies.