Storm, Wind & Hurricane in Pearland, TX
On the Gulf Coast, one storm can involve a homeowners policy, a windstorm policy and a flood policy at once. We document where the wind opened the structure and where the water came from, so each claim rests on evidence.
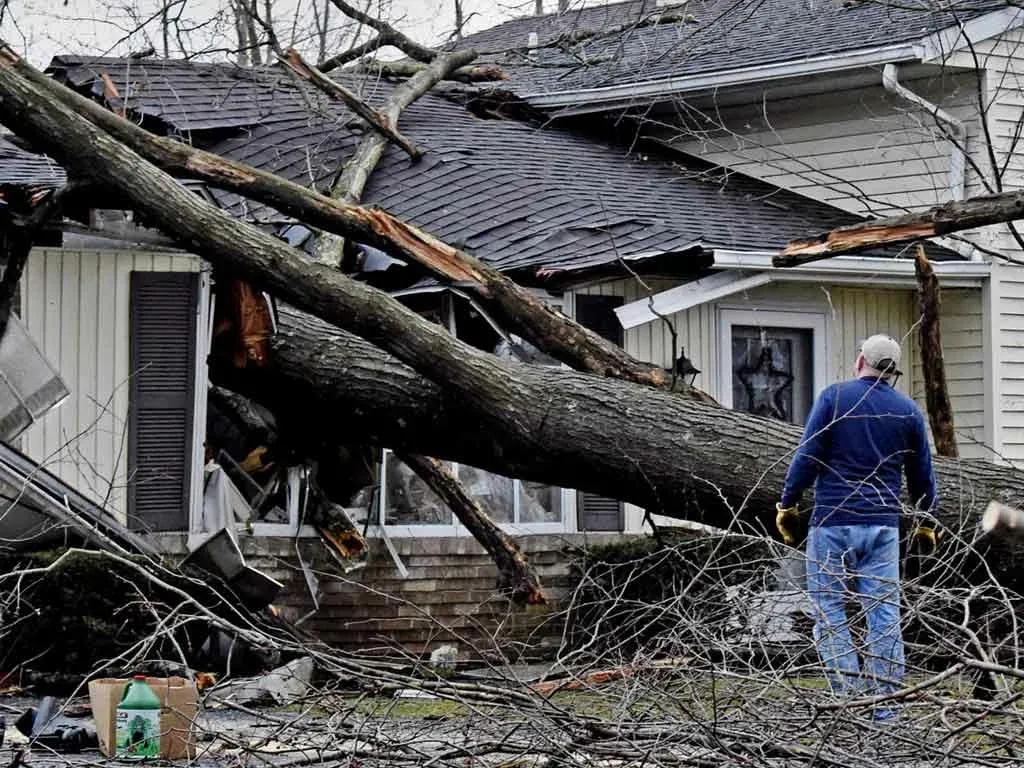
Gulf storms and thunderstorm outflow bring wind to Pearland, Texas, and that wind lifts shingles and drops limbs onto roofs and fences. The city's position across Brazoria and Harris Counties, next to State Highway 288, does not shield it from tropical weather. A strong storm can also fill Clear Creek and its drainage channels, which means one weather event can involve a homeowners policy and a flood policy at the same address.
We split the two. Where wind opened the structure, we record creased and missing shingles, decking uplift, ridge damage and flashing, and we follow the water that came through. Where creek or channel water rose outside, we document the line separately. Newer subdivision roofs still get counted slope by slope, because a roof that is not old can be hurt and age is not a measurement. Fences, sheds and trees that landed on the property are included. Percentage deductibles for wind are common, so we check which one the carrier applied. Save your tarping and board-up receipts. When you are ready, call us or request a free claim review, and we will read the policy together.
What a carrier's inspection tends to miss on storm, wind & hurricane claims in Pearland
- 01
Wind versus water causation
The record that separates a wind-made opening from rising water decides which policy answers for which room.
- 02
The wrong windstorm deductible
Percentage deductibles depend on the insured value and on whether the storm qualified, so the carrier's calculation is worth checking.
- 03
Roof envelope details
Creased and missing shingles, decking uplift, ridge damage and flashing at penetrations are easy to undercount.
- 04
Detached structures and fences
Outbuildings, fences and debris strikes often fall outside the first inspection.
- 05
Interior water from a wind opening
Rain that entered through an opening the wind created may be handled differently from flood water.
- 06
Business income and extra expense
Commercial policies may cover lost income and the cost of operating elsewhere while the property is unusable.
What gets documented on storm, wind & hurricane claims in Pearland
- Direction and pattern of wind damage
- High-water marks and debris lines
- Roof shingles, decking, underlayment and flashing
- Where and when water entered the structure
- Windstorm or named storm deductible and insured value
- Fallen trees and wind-borne debris strikes
- Fences and detached structures
- Interior ceilings, insulation, drywall and flooring
- Receipts for tarping and board-up
Local exposure in Pearland
Tropical storm and thunderstorm wind
Wind from Gulf storms and thunderstorm outflow lifts shingles and drops limbs onto roofs and fences.
Which policy pays for storm damage
Questions about storm, wind & hurricane claims in Pearland
Answer 01
Often in part. Wind damage is commonly covered by a homeowners policy or, in some coastal counties, a TWIA windstorm policy, usually with a percentage deductible. Storm surge and rising water are flood, which standard policies commonly exclude, so one storm can produce claims under two or three policies.
Often in part. Wind damage is commonly covered by a homeowners policy or, in some coastal counties, a TWIA windstorm policy, usually with a percentage deductible. Storm surge and rising water are flood, which standard policies commonly exclude, so one storm can produce claims under two or three policies.
It is a separate deductible that applies to wind losses from certain storms, usually a percentage of the dwelling limit instead of a flat amount. A 2 percent deductible on a home insured for 400,000 dollars is 8,000 dollars. Check which deductible the carrier applied and what value it used.
Causation is a factual question that is answered with evidence, including high-water marks, debris lines, the pattern of material failure, the order of interior damage and the storm timeline at your address. Where wind made an opening first, the damage that followed may be treated differently.
Many homeowners policies cover structure damage from a fallen tree or limb, along with some removal cost, whether it came from your yard or a neighbor's. Haul-off of a tree that hit nothing insured is often limited. Photograph everything before cleanup and keep every receipt for temporary repairs.
It is a separate deductible for wind losses, often a percentage of the dwelling limit instead of a flat amount. The percentage and the value used change the figure. Check your declarations page, and bring it to the free review so we can see whether the carrier applied it correctly.