Storm, Wind & Hurricane in Corpus Christi, TX
On the Gulf Coast, one storm can involve a homeowners policy, a windstorm policy and a flood policy at once. We document where the wind opened the structure and where the water came from, so each claim rests on evidence.
On the Gulf coast, a hurricane can bring wind, rain and surge to a Corpus Christi, TX property in one night, and each can fall under a different policy. Wind may be covered by a homeowners or TWIA windstorm policy, usually with a percentage deductible, while bay surge is flood. For coastal homes near the bay, we record where wind opened the structure and where water rose from outside. For single-family homes with shingle roofs, we count wind damage slope by slope and tie it to dated storm data. Call us or send the free claim review form and we will start with your policies.
What a carrier's inspection tends to miss on storm, wind & hurricane claims in Corpus Christi
- 01
Wind versus water causation
The record that separates a wind-made opening from rising water decides which policy answers for which room.
- 02
The wrong windstorm deductible
Percentage deductibles depend on the insured value and on whether the storm qualified, so the carrier's calculation is worth checking.
- 03
Roof envelope details
Creased and missing shingles, decking uplift, ridge damage and flashing at penetrations are easy to undercount.
- 04
Detached structures and fences
Outbuildings, fences and debris strikes often fall outside the first inspection.
- 05
Interior water from a wind opening
Rain that entered through an opening the wind created may be handled differently from flood water.
- 06
Business income and extra expense
Commercial policies may cover lost income and the cost of operating elsewhere while the property is unusable.
What gets documented on storm, wind & hurricane claims in Corpus Christi
- Direction and pattern of wind damage
- High-water marks and debris lines
- Roof shingles, decking, underlayment and flashing
- Where and when water entered the structure
- Windstorm or named storm deductible and insured value
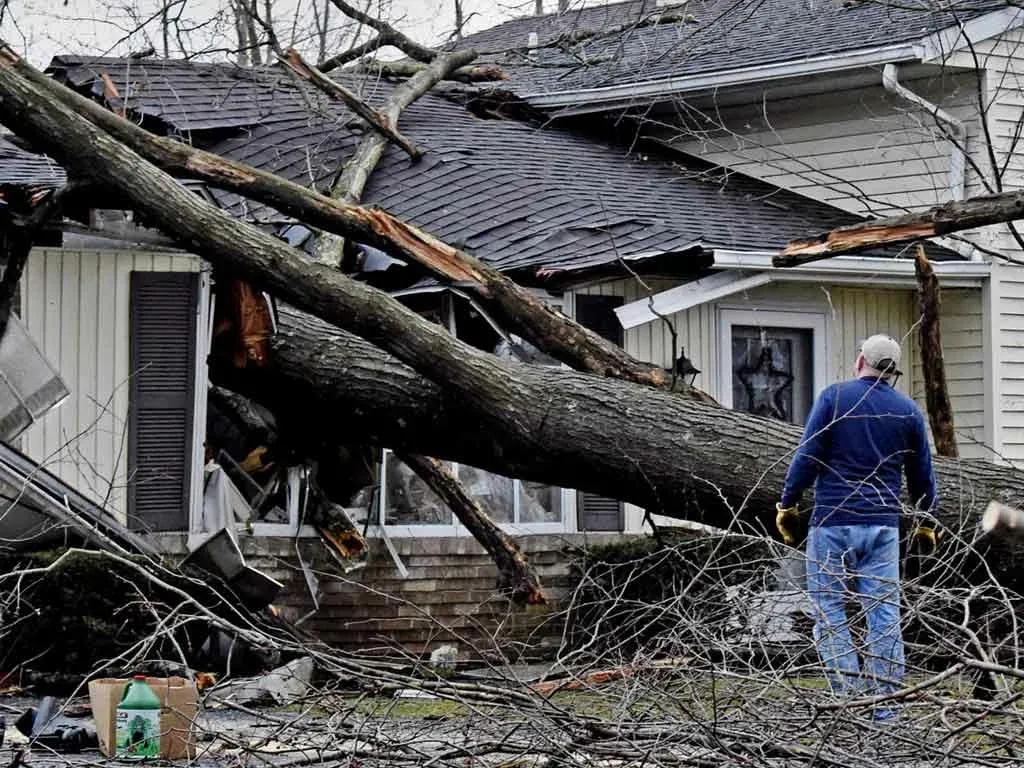
- Fallen trees and wind-borne debris strikes
- Fences and detached structures
- Interior ceilings, insulation, drywall and flooring
- Receipts for tarping and board-up
Local exposure in Corpus Christi
Hurricane wind
Corpus Christi sits directly on the Gulf coast, so hurricane wind is the main driver of roof and structural claims.
Windstorm coverage through TWIA
Nueces County is part of the Texas coast where windstorm coverage may come through the Texas Windstorm Insurance Association.
Which policy pays for storm damage
Questions about storm, wind & hurricane claims in Corpus Christi
Answer 01
Often in part. Wind damage is commonly covered by a homeowners policy or, in some coastal counties, a TWIA windstorm policy, usually with a percentage deductible. Storm surge and rising water are flood, which standard policies commonly exclude, so one storm can produce claims under two or three policies.
Often in part. Wind damage is commonly covered by a homeowners policy or, in some coastal counties, a TWIA windstorm policy, usually with a percentage deductible. Storm surge and rising water are flood, which standard policies commonly exclude, so one storm can produce claims under two or three policies.
It is a separate deductible that applies to wind losses from certain storms, usually a percentage of the dwelling limit instead of a flat amount. A 2 percent deductible on a home insured for 400,000 dollars is 8,000 dollars. Check which deductible the carrier applied and what value it used.
Causation is a factual question that is answered with evidence, including high-water marks, debris lines, the pattern of material failure, the order of interior damage and the storm timeline at your address. Where wind made an opening first, the damage that followed may be treated differently.
Find the deductible on your declarations page, since it is often a percentage of the insured dwelling value instead of a flat amount. Then compare it with what the carrier applied and what value it used. We review that math with you.
Photograph and video the damage first, inside and out. Make only the repairs needed to prevent more damage, such as tarping, and keep every receipt. Do not discard damaged material until it has been documented, and report the loss as soon as the property is safe.