Flood Damage in Friendswood, TX
Flood is a separate kind of insurance with its own forms, its own limits and a sworn Proof of Loss that has to be complete. We prepare flood claims with the documentation that requires, and we record the evidence before demolition removes it.
Clear Creek runs through Friendswood, TX, and when it rises, flood claims follow. Hurricane Harvey in 2017 put water into neighborhoods along the creek that had not flooded before, so many owners learned about flood insurance the hard way. Flood is usually covered by a separate NFIP or private flood policy, not the standard homeowners policy, and that policy has its own forms and a sworn Proof of Loss.
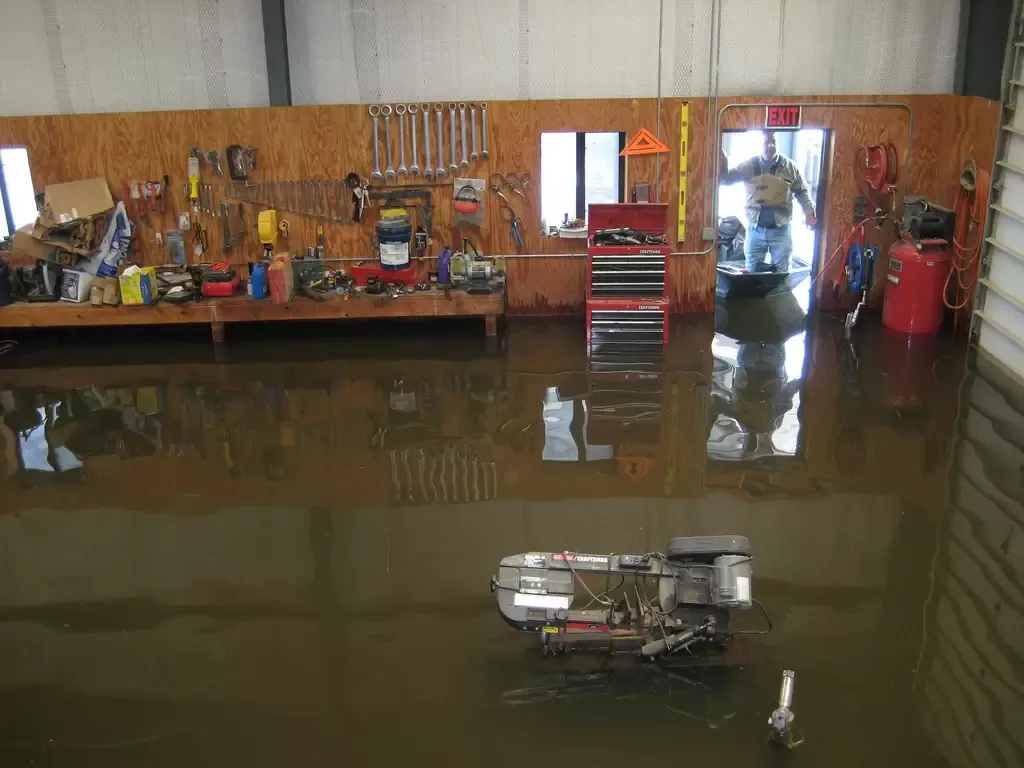
Brick exteriors add a wrinkle. Water can wick into brick-veneer walls and insulation, and a quick look from outside will miss it. We measure the water line in every room, record flood cut heights and the condition of subfloors, and note submerged HVAC units, water heaters and electrical panels before demolition removes the evidence. Then we help you build a contents schedule and a complete Proof of Loss.
The city sits in Galveston and Harris Counties, and your policy sets the deadlines that apply to you. Do not wait on paperwork. If your Friendswood flood claim is open, denied or short, call or send the free review form and we will tell you what the file is missing.
What a carrier's inspection tends to miss on flood damage claims in Friendswood
- 01
Water line and depth, room by room
Once drywall is cut, the record of how high the water reached is gone, so it has to be measured before demolition.
- 02
Mechanical and electrical systems
Submerged HVAC units, water heaters and electrical panels can be unsafe to reuse yet get scoped as cleanable.
- 03
Contents without a schedule
Where contents coverage was bought, a room-by-room list of damaged property is what supports it.
- 04
A Proof of Loss that is incomplete
The NFIP works from a sworn form, and a form without supporting estimates can be returned or denied on procedure.
- 05
Increased Cost of Compliance
This NFIP benefit can help with elevating, floodproofing or demolishing a substantially damaged structure, and it is often never filed.
What gets documented on flood damage claims in Friendswood
- Water line height in every room
- Flood cut heights, subfloor and joist condition
- Insulation removal and antimicrobial treatment
- Submerged HVAC, water heater and electrical panel
- Contents schedule by room
- Debris list kept before anything goes to the curb
- Wind versus water evidence where both are in play
- Sworn Proof of Loss with supporting estimates
- Substantial damage letter and Increased Cost of Compliance filing
Local exposure in Friendswood
Clear Creek flooding
Clear Creek runs through Friendswood, and Hurricane Harvey in 2017 flooded neighborhoods along it that had not flooded before.
Which policy pays for flood damage
Questions about flood damage claims in Friendswood
Answer 01
Standard Texas homeowners policies commonly exclude flood, including storm surge, bayou overflow and sheet flow. Flood coverage usually comes from an NFIP policy or a private flood policy. Water entering through a wind-damaged roof is a different cause of loss and may fall under the homeowners or windstorm policy.
Standard Texas homeowners policies commonly exclude flood, including storm surge, bayou overflow and sheet flow. Flood coverage usually comes from an NFIP policy or a private flood policy. Water entering through a wind-damaged roof is a different cause of loss and may fall under the homeowners or windstorm policy.
A Texas-licensed public insurance adjuster can represent a policyholder on an NFIP claim, including preparing the sworn Proof of Loss and its supporting documents. Because the program has strict documentation and timing rules, having the file assembled carefully the first time matters.
It is an NFIP benefit that contributes toward elevating, relocating, floodproofing or demolishing a building your local floodplain official has declared substantially damaged. It is separate from the building payment. The determination and the filing are handled by different offices, so it is easy to miss.
Usually not. Standard Texas homeowners policies commonly exclude flood, which means rising surface water like creek overflow. Coverage typically comes from a separate NFIP or private flood policy. If rain came in through a wind-damaged roof, that may be handled differently, so we check how the water entered.
Photograph and video the water line in every room, the height of any marks on walls and the condition of floors, appliances and the electrical panel. Keep a list of what is thrown out. Once drywall is cut and debris reaches the curb, proof of how high the water rose is hard to rebuild.